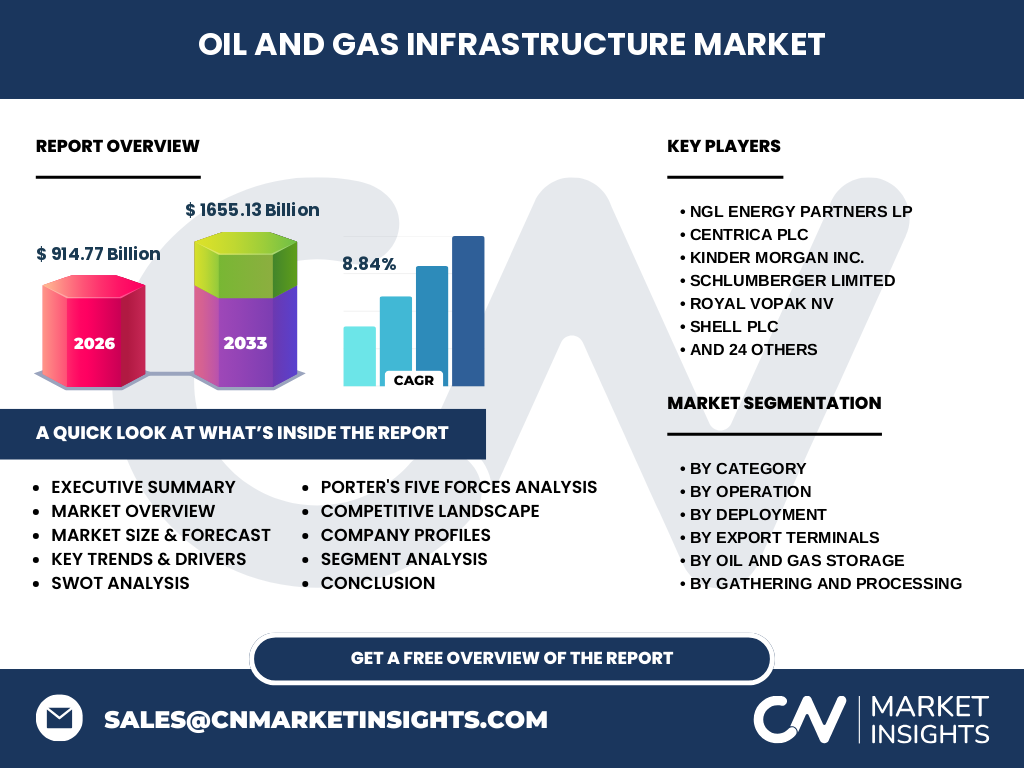
Overview of the Oil And Gas Infrastructure Market scope and significance
The Oil And Gas Infrastructure Market serves as the global circulatory system for energy, encompassing extraction, transport, and processing assets. Spanning from wellhead equipment to LNG export terminals, this sector is critical for energy security. Our research indicates that these capital-intensive systems are essential for bridging the gap between upstream production sites and global downstream markets, ensuring reliable commodity delivery.
Structural Growth Drivers and Market Constraints
The market faces a dual-force landscape. Key drivers include rising global demand and the necessity for midstream optimization, while regulatory hurdles from agencies like the EPA and FERC pose significant constraints. Operational challenges, such as the maintenance of aging steel pipelines, create a critical opportunity for digital infrastructure retrofits, driving long-term investment in smart monitoring and automated flow-control technologies.
Emerging Trends in Oil And Gas Infrastructure
We are witnessing a paradigm shift toward decarbonization and infrastructure repurposing. Major players like Shell PLC and TotalEnergies SE are increasingly integrating carbon capture and storage (CCS) into their existing network footprints. This trend toward high-efficiency, low-emission infrastructure is not merely aesthetic; it is a strategic requirement for operators to maintain their 'social license to operate' under increasingly stringent global ESG mandates.
COVID-19 Impact and Recovery Analysis
The pandemic caused a temporary stagnation in infrastructure development due to disrupted supply chains and plummeting commodity prices. However, our analysis shows a robust recovery trajectory as industrial demand returned. By 2026, the market reached a valuation of 914.77 Billion, highlighting the industry's resilience and its ability to re-calibrate logistics and capital expenditure cycles in a post-pandemic economic climate.
Competitive Benchmarking and Strategic Dynamics
The competitive field is highly concentrated, featuring giants like Kinder Morgan Inc. and Energy Transfer LP. Strategic focus has shifted toward asset optimization rather than pure expansion. Companies are leveraging vertical integration, combining gathering and processing capabilities with crude oil export terminals to hedge against commodity price volatility. This integration offers a distinct competitive moat compared to smaller, fragmented regional service providers.
Executive Summary of the Oil And Gas Infrastructure Market
The Oil And Gas Infrastructure Market is on an aggressive growth trajectory, projected to reach 1655.13 Billion by 2033. With a steady CAGR of 8.84%, the sector remains a foundational pillar of the global economy. Strategic success requires navigating complex regulatory landscapes while investing in resilient storage and high-capacity export infrastructure to meet the shifting geopolitical demand for energy security.
Market Forecast 2027 to 2033
Based on our proprietary data models, we project the market to expand from 2027 to 2033, reaching a significant milestone of 1655.13 Billion. This expansion is underpinned by sustained investment in Natural Gas Liquids (NGL) pipelines and LNG export terminals. The 8.84% CAGR reflects a sustained capital injection into essential energy corridors needed to support global industrial output and energy transition stability.
Comprehensive Segmentation Analysis
Segmentation allows for precise market evaluation across Onshore and Offshore deployments. Key categories include:
- Surface and Lease Equipment
- Gathering and Processing facilities
- Pipelines (Crude, Gas, NGL)
- Storage (ASTs and UGS)
- Refining and Product Transport
Geographic Distribution and Performance
The market displays strong regional variances. North America remains a leader in pipeline expansion and processing technology, while Middle Eastern regions focus on massive export terminal capacity. The performance of these regions is intrinsically linked to local extraction capabilities and access to deep-water ports. Our data indicates that regional regulatory environment maturity remains the primary predictor of successful infrastructure lifecycle management.
In-depth Review of Regional Dynamics
Europe faces unique constraints due to supply diversification requirements, pushing investment toward LNG storage tanks. In contrast, Asia-Pacific serves as the primary growth engine for new refining and transportation systems. Understanding these localized hurdles—such as EU energy directives versus Asian industrial rapid development—is critical for stakeholders looking to optimize their regional asset portfolio and mitigate logistical risks inherent in cross-border energy transport.
Strategic Positioning of Leading Companies
Firms like Schlumberger Limited and Baker Hughes Company dominate the technology-intensive surface equipment sector. Conversely, Royal Vopak NV holds a strategic stronghold in the storage domain. These companies differentiate themselves through technical innovation, such as automated pumping systems or advanced corrosion-resistant material science, ensuring that their infrastructure assets maintain operational superiority over decades of intensive use in harsh field environments.
Porter's Five Forces Assessment
The threat of new entrants is low due to immense capital intensity and strict regulatory barriers. Supplier power is moderate, concentrated among specialized steel and valve manufacturers. However, the competitive rivalry is intense, as major firms vie for limited pipeline rights-of-way and regulatory approvals. Buyers possess significant influence, particularly in commodity-rich regions, where infrastructure access is negotiated through long-term service agreements.
SWOT Analysis of the Industry
The market's Strengths lie in its essential nature and vast asset base. Weaknesses include high debt-to-equity ratios for major operators. Opportunities abound in the digitalization of pipelines and expansion of LNG infrastructure. However, Threats persist, specifically from geopolitical instability and the accelerated transition toward renewable energy, which could potentially strand current assets if not properly managed through strategic repurposing programs.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material procurement for wellhead equipment, progressing through gathering and processing. Transportation systems—specifically NGL pipelines—serve as the vital link to refineries and, ultimately, to global export terminals. Each node in this chain adds value, from primary extraction monitoring by firms like Aker Solutions ASA to the high-throughput logistics handled by global engineering leaders like Bechtel Corporation.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize the LNG export and NGL pipeline segments, where growth indicators are strongest. Based on our analysis, companies demonstrating a clear strategy for infrastructure digitalization and carbon-neutral facility operations represent the most resilient targets. Diversifying into regions with clear legal frameworks for energy projects—rather than politically volatile corridors—is our primary recommendation for mitigating long-term capital risk and maximizing returns.
Conclusion and Strategic Takeaways
The Oil And Gas Infrastructure Market is a stable yet evolving landscape poised for significant growth, hitting 1655.13 Billion by 2033. Success relies on balancing traditional infrastructure strength with the emerging need for low-emission technologies. Stakeholders should focus on geographical diversification and the integration of smart grid principles to navigate the next decade of energy demand successfully.
Research Methodology for Baseline Estimates
Our baseline estimates are triangulated using a multi-dimensional approach. We integrate verified trade registry data, conduct primary interviews with C-suite stakeholders, and synthesize secondary macroeconomic indicators. This method accounts for local market constraints and logistical hurdles, ensuring that our figures accurately reflect real-world performance, minimizing the noise of speculative projections and providing a granular, reliable view of the infrastructure landscape.
Scope and Parameters of the Research
This research covers global Oil And Gas Infrastructure Market developments, focusing on assets from wellhead to export terminal. Excluded from this scope are retail-end automotive fueling stations and upstream exploration permits, focusing instead on the midstream and downstream infrastructure backbone. The analysis is bounded by current technology trends and documented regulatory frameworks as of the 2027 forecast initiation point.
Recent Market Developments and Strategic Moves
Significant recent activity includes large-scale partnerships between engineering firms like Fluor Corporation and energy producers to advance modular refining technology. Furthermore, strategic announcements regarding the expansion of crude oil export terminals highlight the industry's focus on export agility. These moves suggest a broader push toward modularity and efficiency, allowing operators to scale infrastructure capacity rapidly in response to sudden fluctuations in global crude pricing.